
Flood Insurance Georgia
Your homeowners policy doesn't cover flood damage. Georgia risk spans Atlanta metro drainage floods, Chattahoochee and Savannah river basins, and coastal storm surge near Savannah and Brunswick.
Get your free flood quote
Get Your Instant Flood Insurance Quote
Continue with Neptune Flood for an online flood quote after TCDS saves your request.
Continue with Neptune Flood after sharing your contact details with TCDS. A local agent can help if you have questions. Your information is not added to the referral link. The provider controls eligibility, pricing, and policy confirmation; starting a quote does not activate coverage.
Prefer to talk first? Call TCDS at (205) 847-5616.
TCDS does not sell your information. Continuing does not obligate you to purchase coverage.
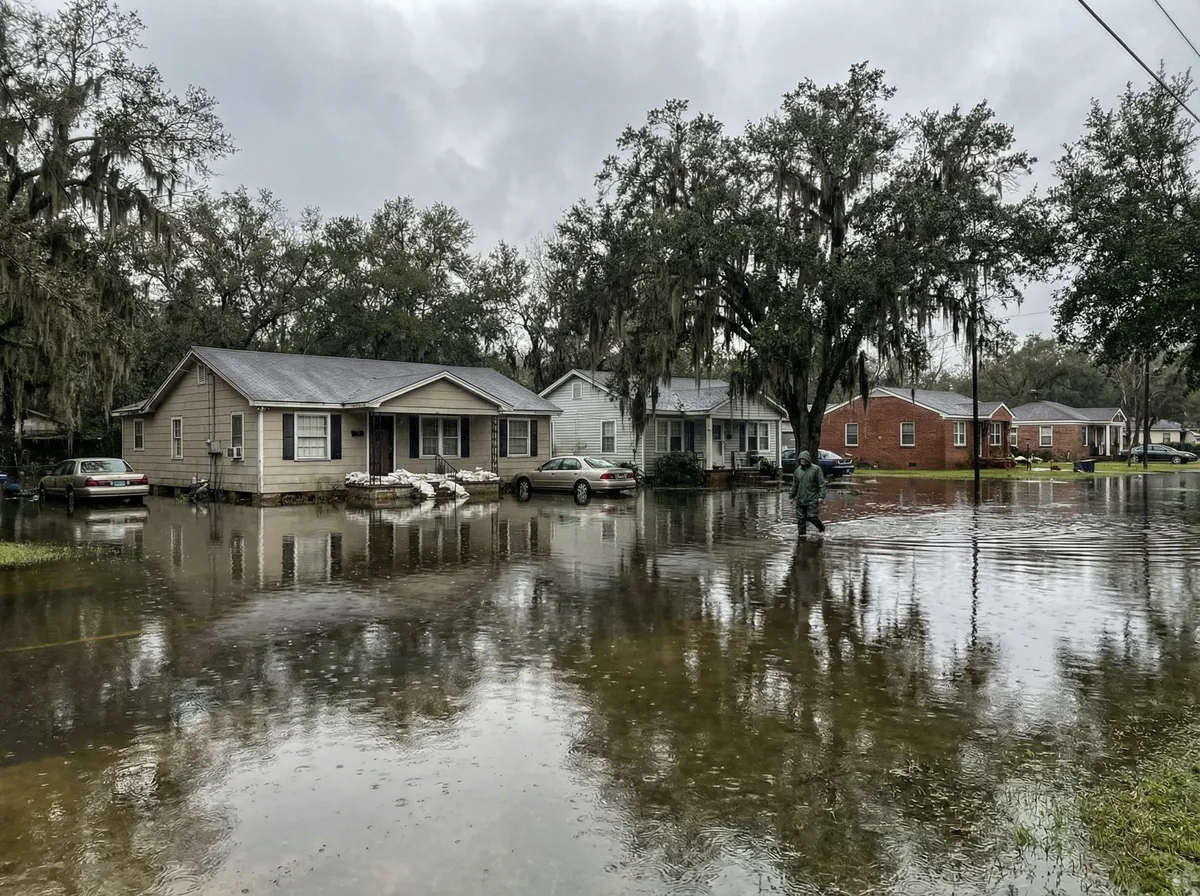
Why Georgia Homeowners Need Flood Insurance
Homeowners insurance does NOT cover flood damage. Georgia losses come from intense rain over impermeable metro surfaces, river crests, and coastal surge — including homes outside high-risk FEMA polygons.
- Atlanta metro flash flooding from heavy rain and aging drainage
- Savannah / Brunswick / coastal counties — storm surge is flood-only
- Chattahoochee, Savannah, and Altamaha river floodplains
- About 25% of NFIP claims nationally come from outside high-risk zones
What Flood Insurance Covers
Foundation, walls, electrical, plumbing, HVAC, and attached structures.
NFIP cap: $250,000 building. Private carriers often go much higher.
Furniture, electronics, clothing, appliances, and personal property.
NFIP cap: $100,000 contents. Private options can reach $250K–$850K+.
Georgia Flood Insurance Cost
Georgia's statewide NFIP average is roughly $889/year. Coastal and SFHA homes cost more; many metro Zone X homes can access Preferred Risk pricing or competitive private quotes.
NFIP normally has a 30-day waiting period, with specified exceptions. Don't wait until a storm is approaching.
Georgia Flood Insurance Cost by Market (2026)
Georgia premiums vary from inland metro flash-flood risk to coastal surge counties. Private markets often compete hard outside Zone V/A coastal cores.
| Georgia Market | Typical premium range | Risk profile |
|---|---|---|
| Atlanta / Fulton & DeKalb | Often $600–$1,500/yr | Urban flash flood, creek overflow |
| Marietta / Cobb Co | Often $550–$1,400/yr | Metro drainage + stream corridors |
| Savannah / Chatham Co | Often $900–$2,200/yr | Coastal surge + tidal flooding |
| Augusta / Richmond Co | Often $650–$1,500/yr | Savannah River basin |
| Coastal islands / Glynn area | Often $1,000–$2,500+/yr | Surge and VE/AE exposure |
| Zone X Preferred Risk (eligible) | Often $350–$700/yr | Moderate/low mapped risk — still worth quoting |
Source: FEMA NFIP program data and regional summaries. Actual rates depend on zone, elevation, construction, and limits. Compare NFIP and private every renewal.
Lower Georgia Flood Premiums: 4 Practical Steps
Risk Rating 2.0 changed many Georgia renewals. Shopping private carriers beside NFIP is the fastest way to find a better number for Atlanta and inland homes.
Private Flood Insurance Carriers Available in Georgia
Private flood is active across Georgia. Coastal homes often need higher limits than NFIP caps; metro Zone X homes may find private cheaper than NFIP.
| Carrier | Building limit | Contents limit | Strengths in Georgia |
|---|---|---|---|
| Neptune Flood | Up to $4M | Up to $500K | High limits and modern quoting — strong for GA suburban and coastal homes |
| Aon Edge | Up to $1.25M | Up to $850K | Higher contents caps; competitive when NFIP $100K contents is too low |
| Wright FocusFlood | Up to $1M+ | Up to $500K | Established flood claims operations |
| Flow Flood | Up to $1M | Up to $250K | Speed for lower-risk / newer homes |
| NFIP (FEMA) | $250K cap | $100K cap | Lender standard across Georgia including coastal SFHA |
30-Day Waiting Period: Exceptions That Matter in Georgia
NFIP's 30-day wait is critical before hurricane season on the Georgia coast and before spring severe-weather floods inland.
Source: FEMA/NFIP waiting-period exceptions. Confirm the applicable effective-date rules for your transaction.
1. Qualifying mortgage transactions
NFIP can waive the wait when coverage is purchased in connection with making, increasing, extending, or renewing a mortgage loan. Application and payment timing requirements still apply.
2. Qualifying map revisions
A building newly mapped into a Special Flood Hazard Area may qualify for a one-day wait if coverage is purchased within the applicable window. Confirm the map date and eligibility.
3. Renewal increases and post-wildfire flooding
Certain increases offered on an NFIP renewal bill can take effect at renewal without the normal wait. Qualifying flooding affected by wildfire on federal land may have a one-day wait, subject to purchase timing and claim review. Private insurers set their own waiting periods and binding rules.
NFIP vs Private Flood
For most Georgia homeowners: Get quotes from both NFIP and private. Premiums for the same address can differ by 30–50%.
For high-risk zones: Compare carefully — NFIP may be more affordable, but private replacement-cost contents can save thousands after a claim.
For high-value homes: If the dwelling exceeds $250,000 rebuild cost, private limits usually matter more than NFIP caps.
Both paths often involve a waiting period. Get covered before the next flood watch.
Georgia Flood Risk Areas
- • Savannah, Brunswick, and coastal counties (storm surge)
- • Atlanta metro creek and drainage corridors
- • Chattahoochee and Savannah river floodplains
- • Augusta and other river cities after heavy upstream rain
- • Heavy rainfall can overwhelm drainage systems anywhere
- • Flash floods occur outside mapped zones
- • New construction changes water flow patterns
- • About 25% of NFIP claims come from moderate/low-risk areas
Questions about Georgia flood insurance?
We'll confirm your zone, compare NFIP and private, and find coverage that fits your home.
Frequently asked questions
How much does flood insurance cost in Georgia?
Georgia's average NFIP flood policy is about $889 per year in industry summaries of FEMA data. Coastal SFHA and older low-elevation homes cost more; many Atlanta metro Zone X homes can find Preferred Risk or private quotes well below high-risk rates.
Is flood insurance required in Georgia?
Lenders require flood insurance for federally backed mortgages in high-risk FEMA zones. It is optional elsewhere but smart for metro flash-flood and coastal surge exposure. Home insurance never covers flood.
Does Georgia homeowners insurance cover flooding?
No. Standard Georgia homeowners policies exclude flood and rising water. Coastal storm surge near Savannah is covered only by a flood policy — not home or wind alone.
How long until Georgia flood insurance takes effect?
Standard NFIP policies have a 30-day waiting period. Some private flood policies may be shorter. Purchase ahead of hurricane season and major rain systems.
NFIP or private flood in Georgia?
NFIP is standardized and widely accepted by lenders. Private carriers can offer higher limits or lower premiums for some homes. TCDS compares both for Georgia properties.
How do I check my Georgia flood zone?
Use FEMA's Flood Map Service Center (msc.fema.gov) with your address, or request a quote and we will pull zone context while shopping NFIP and private markets.









































