Flood Insurance Alabama
Your homeowners policy doesn't cover flood damage. With Alabama's rivers, heavy rainfall, and flash flood risk, separate flood insurance is essential to protect your home and belongings.
Get your free flood quote
Get Your Instant Flood Insurance Quote
Continue with Neptune Flood for an online flood quote after TCDS saves your request.
Continue with Neptune Flood after sharing your contact details with TCDS. A local agent can help if you have questions. Your information is not added to the referral link. The provider controls eligibility, pricing, and policy confirmation; starting a quote does not activate coverage.
Prefer to talk first? Call TCDS at (205) 847-5616.
TCDS does not sell your information. Continuing does not obligate you to purchase coverage.
Why Alabama Homeowners Need Flood Insurance
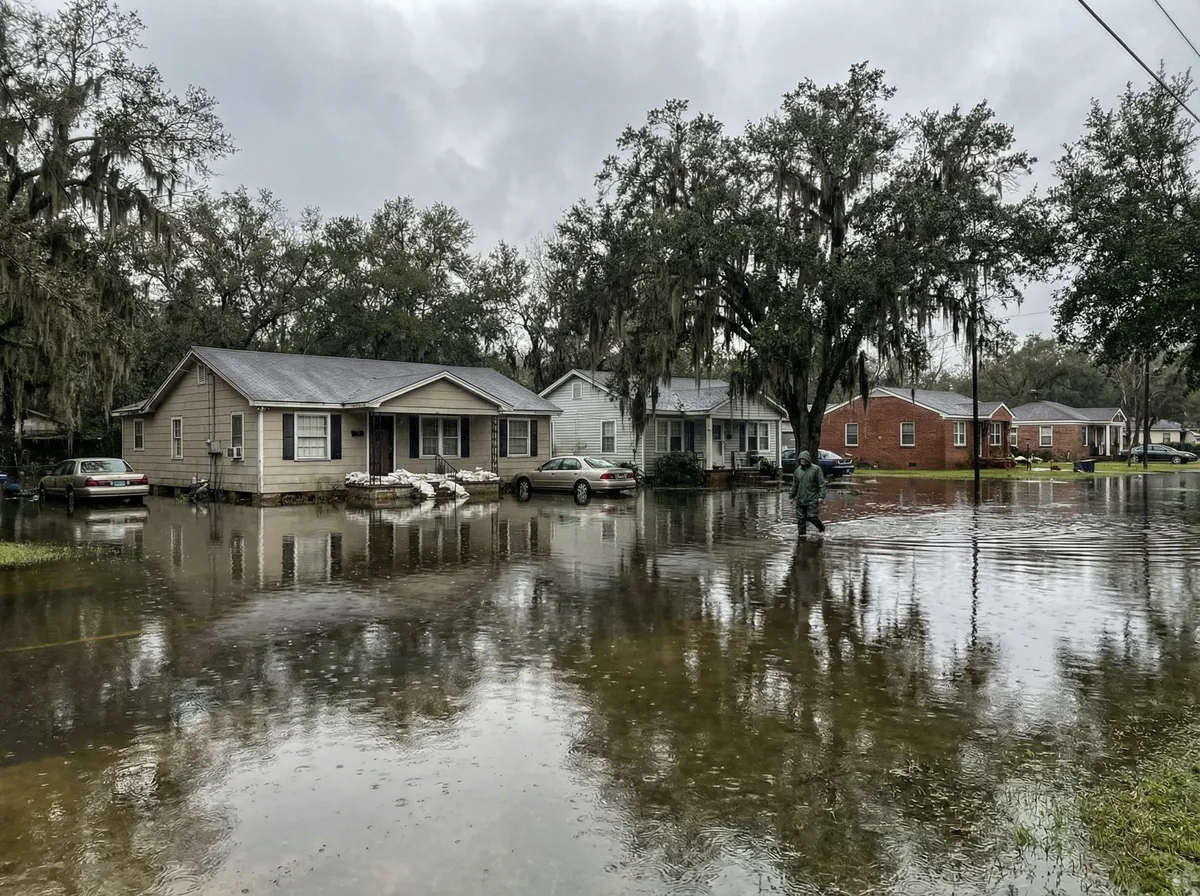
Homeowners insurance does NOT cover flood damage. Many Alabama homeowners discover this only after a loss. With river systems, Gulf exposure, and flash flood potential, flood risk is real across Alabama—not just in designated flood zones.
- Alabama averages 50+ flash flood events per year
- Gulf storm surge in Mobile and Baldwin counties is flood-only coverage
- Roughly 25% of NFIP claims nationally come from outside high-risk zones
- Risk Rating 2.0 has increased many Alabama NFIP premiums sharply
What Flood Insurance Covers
Foundation, walls, electrical, plumbing, HVAC, and attached structures.
NFIP cap: $250,000 building. Private carriers often go much higher.
Furniture, electronics, clothing, appliances, and personal property.
NFIP cap: $100,000 contents. Private options can reach $250K–$850K+.
Alabama Flood Insurance Cost
Typical low-to-moderate risk homes often land in the $400–$700/year range; high-risk zones run higher. Preferred Risk Policies can start near $300–$500/year for eligible Zone X homes.
NFIP normally has a 30-day waiting period, with specified exceptions. Don't wait until a storm is approaching.
Alabama Flood Insurance Cost by County (2026)
The Alabama average NFIP premium is $825–$879/year, slightly below the $899 national average. Premiums vary dramatically by county — from ~$319 in rural Perry County to ~$1,560 in Birmingham. Private flood rates can run 20–40% lower for low-to-moderate-risk homes.
| Alabama County / City | Typical premium range | Risk profile |
|---|---|---|
| Birmingham (Jefferson Co) | ~$1,560/yr | Urban + flash flood, CRS discount up to 25% |
| Mobile County | ~$1,484/yr | Gulf storm surge + hurricane exposure |
| Baldwin County | ~$1,087/yr | Coastal + barrier island flood risk |
| Tuscaloosa County | ~$950/yr | Black Warrior River + storm-driven flooding |
| Montgomery | ~$760/yr | Alabama River, moderate risk |
| Perry County (rural) | ~$319/yr | Lower density, lower average premium |
Source: FEMA NFIP rate data and regional analysis. Your actual premium depends on flood zone, elevation, year built, and limits. Risk Rating 2.0 increased many Alabama NFIP premiums; compare private options every renewal.
Cheap Flood Insurance in Alabama: 4 Ways to Lower Your Premium
If your NFIP renewal jumped under Risk Rating 2.0, premiums for the same home can vary 30–50% between NFIP and private carriers. Here's how to bring Alabama flood cost down without losing coverage.
Private Flood Insurance Carriers Available in Alabama
Four major private carriers write residential flood in Alabama alongside NFIP. Each has different sweet spots versus NFIP's $250K building / $100K contents cap.
| Carrier | Building limit | Contents limit | Strengths in Alabama |
|---|---|---|---|
| Neptune Flood | Up to $4M | Up to $500K | Replacement cost on contents, instant online quote, ALE, pool repair coverage |
| Aon Edge | Up to $1.25M | Up to $850K | Strong contents limits; competitive in coastal AL (Mobile, Baldwin) |
| Wright FocusFlood | Up to $1M+ | Up to $500K | Available in Alabama since 2023; strong claims operation via Wright NFIP servicing |
| Flow Flood | Up to $1M | Up to $250K | Quick instant quotes; competitive on newer homes outside Zone A/V |
| NFIP (FEMA) | $250K cap | $100K cap | Required by most mortgages; available in all Alabama flood zones |
30-Day Waiting Period: 3 Exceptions That Apply in Alabama
NFIP's 30-day waiting period catches many Alabama homeowners off guard — especially when a tropical system is in the Gulf.
Source: FEMA/NFIP waiting-period exceptions. Confirm the applicable effective-date rules for your transaction.
1. Qualifying mortgage transactions
NFIP can waive the wait when coverage is purchased in connection with making, increasing, extending, or renewing a mortgage loan. Application and payment timing requirements still apply.
2. Qualifying map revisions
A building newly mapped into a Special Flood Hazard Area may qualify for a one-day wait if coverage is purchased within the applicable window. Confirm the map date and eligibility.
3. Renewal increases and post-wildfire flooding
Certain increases offered on an NFIP renewal bill can take effect at renewal without the normal wait. Qualifying flooding affected by wildfire on federal land may have a one-day wait, subject to purchase timing and claim review. Private insurers set their own waiting periods and binding rules.
NFIP vs Private Flood
For most Alabama homeowners: Get quotes from both NFIP and private. Premiums for the same address can differ by 30–50%.
For high-risk zones: Compare carefully — NFIP may be more affordable, but private replacement-cost contents can save thousands after a claim.
For high-value homes: If the dwelling exceeds $250,000 rebuild cost, private limits usually matter more than NFIP caps.
Both paths often involve a waiting period. Get covered before the next flood watch.
Alabama Flood Risk Areas
- • Mobile and Baldwin County (coastal storm surge)
- • Areas near Coosa, Alabama, and Tombigbee rivers
- • Birmingham metro (flash flood potential)
- • Low-lying areas near creeks and streams
- • Heavy rainfall can overwhelm drainage systems anywhere
- • Flash floods occur outside mapped zones
- • New construction changes water flow patterns
- • About 25% of NFIP claims come from moderate/low-risk areas
Questions about Alabama flood insurance?
We'll confirm your zone, compare NFIP and private, and find coverage that fits your home.
Frequently asked questions
How much does flood insurance cost in Alabama?
The average Alabama flood insurance premium is $825-$879 per year according to FEMA NFIP data — slightly below the $899 national average. Birmingham averages ~$1,560/yr, Mobile ~$1,484/yr, Montgomery ~$760/yr. Private carriers (Neptune, Aon Edge, Wright FocusFlood, Flow) often beat NFIP for low-to-moderate-risk Alabama homes.
What is the cheapest flood insurance in Alabama?
For low-to-moderate-risk homes (Zones B, C, X), the NFIP Preferred Risk Policy starts around $300-$500/year. Private carriers like Neptune and Flow often beat that for newer, elevated homes. Compare NFIP and 2-3 private quotes side-by-side.
Do I need flood insurance in Alabama?
You're required to carry flood insurance if you're in a high-risk zone (A or V) with a federally-backed mortgage. Even if not required, FEMA reports about 25% of flood claims come from moderate-to-low-risk areas. Alabama's flood-prone counties include Jefferson, Houston, Mobile, Choctaw, Baldwin, Coffee, Morgan, and Tuscaloosa.
Does homeowners insurance cover flooding?
No. Standard homeowners insurance does NOT cover flood damage. You need a separate flood policy through the NFIP or a private flood carrier — the single most common gap in Alabama homeowners' coverage.
How do I know my flood zone in Alabama?
Check FEMA's Flood Map Service Center at msc.fema.gov by entering your address. Zones A and V are high-risk; Zones B, C, and X are moderate-to-low risk but can still flood. TCDS can also look up your zone when you request a quote.
Is there a waiting period for flood insurance in Alabama?
Yes — NFIP has a 30-day waiting period. Exceptions: new mortgage closing, certain map revisions, and rare post-wildfire rules. Private carriers like Neptune may offer shorter waiting periods.