Hurricane Season Insurance Prep for Mobile/Baldwin County
Mobile and Baldwin County face hurricane risk every summer. Here's what homeowners insurance covers (and doesn't), how wind deductibles work, and why you need separate flood insurance.
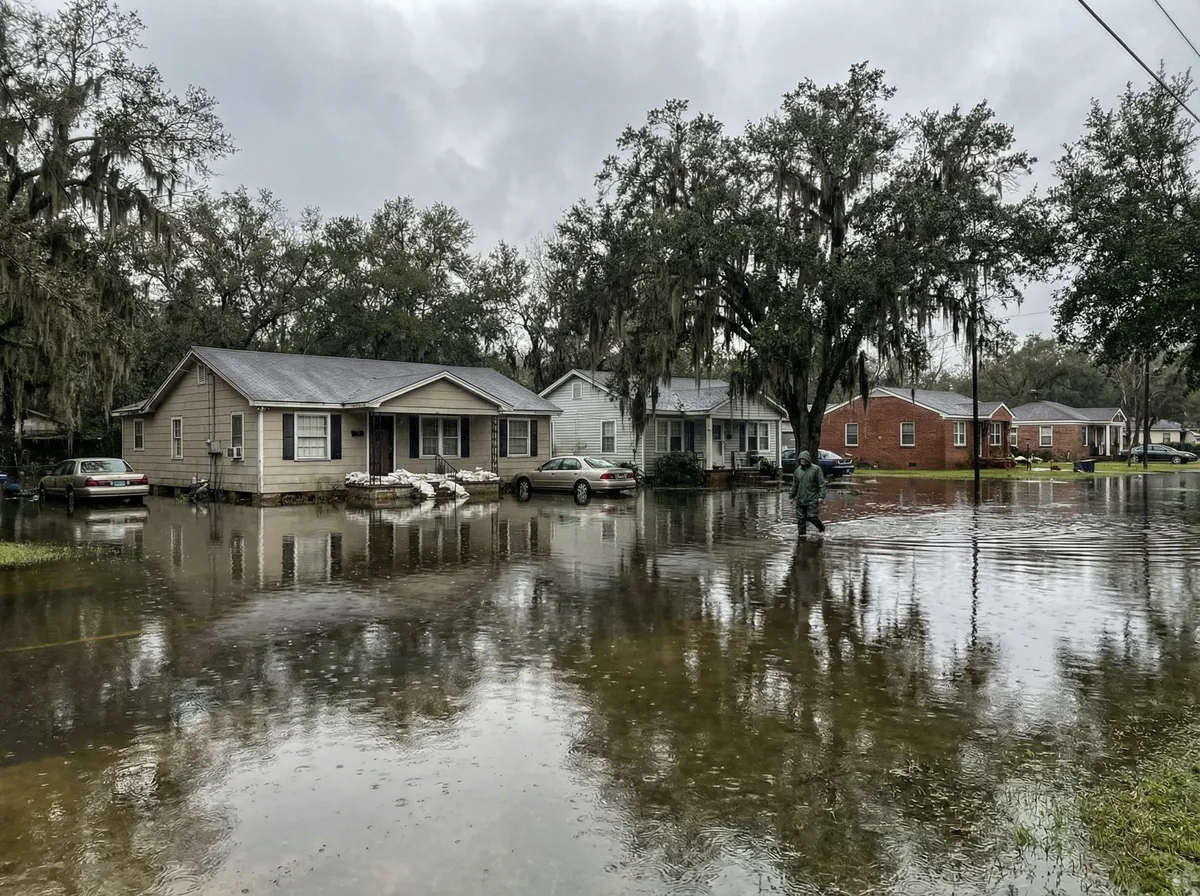
If you live in Mobile, Fairhope, Daphne, Gulf Shores, or anywhere in Baldwin County, hurricane season isn't a hypothetical threat. Hurricane Sally (2020), Hurricane Zeta (2020), and Hurricane Ivan (2004) all caused billions in damage along Alabama's Gulf Coast. Yet most homeowners don't fully understand what their insurance covers until after a storm hits.
This article explains what homeowners insurance covers during hurricane season, what it doesn't, and the critical coverage gaps that leave Mobile and Baldwin County homeowners underinsured.
What Homeowners Insurance Covers After a Hurricane
Good news first: Standard homeowners insurance (HO-3 policy) covers wind damage from hurricanes. This includes:
- Roof damage from wind or flying debris
- Exterior walls, siding, and windows blown out by wind
- Interior damage from rain entering through wind-damaged roof or walls
- Detached structures like garages, sheds, and fences
- Personal property damaged by wind or rain (if wind created the opening)
Important distinction: If hurricane winds damage your roof and rain pours in, that's covered. But if floodwater enters your home from the ground up, that's not covered under homeowners insurance—you need separate flood insurance.
What Homeowners Insurance Does NOT Cover
1. Flood Damage (The #1 Coverage Gap)
Homeowners insurance does NOT cover flood damage—even if the flood is caused by a hurricane. This is the most common and costly coverage gap for Mobile and Baldwin County homeowners.
What counts as "flood damage"?
- Storm surge from Mobile Bay or the Gulf of Mexico
- Rising water that enters your home from the ground up
- Overflowing rivers, creeks, or drainage systems
- Heavy rainfall that pools and enters your home from ground level
During Hurricane Sally (2020), many Mobile and Baldwin County homes experienced both wind damage (covered) and flood damage (not covered). Homeowners without flood insurance had to pay for water damage repairs out of pocket—often $50,000-150,000+.
Solution: Purchase a separate flood insurance policy through the National Flood Insurance Program (NFIP) or a private carrier. If you're in Mobile or Baldwin County, flood insurance isn't optional—it's essential.
2. Evacuation and Temporary Living Expenses (Limited)
Most homeowners policies include Additional Living Expenses (ALE) coverage, which pays for hotel, meals, and temporary housing if your home is uninhabitable after a hurricane. However:
- ALE only applies if your home is damaged and uninhabitable. If you evacuate but your home isn't damaged, ALE doesn't pay.
- ALE has time and dollar limits—typically 12-24 months or 20-30% of your dwelling coverage, whichever comes first.
- Evacuation costs before the storm (hotel, gas, meals) are not covered.
3. Vehicle Damage
If a hurricane destroys your car, truck, or boat, homeowners insurance doesn't cover it. Vehicle damage is covered under your auto insurance policy's comprehensive coverage.
After Hurricane Sally, we saw dozens of Mobile homeowners surprised that their flooded vehicles weren't covered under their homeowners claim. If you only carry liability auto insurance (no comprehensive), you'll pay to replace your vehicle yourself.
4. Landscaping and Trees (Limited)
Most homeowners policies provide limited coverage for trees and landscaping—typically $500-1,000 per tree, up to 5% of your dwelling coverage. If a hurricane uproots multiple trees or destroys your landscaping, you'll likely pay most of the replacement cost yourself.
Understanding Your Hurricane/Wind Deductible
Here's the coverage detail that catches most Mobile and Baldwin County homeowners off guard: hurricane and wind damage have a separate, higher deductible than other types of claims.
While your standard deductible for theft or fire might be $1,000, your hurricane/wind deductible is typically 2-5% of your dwelling coverage. On a $300,000 home:
- 2% deductible = $6,000 out of pocket
- 3% deductible = $9,000 out of pocket
- 5% deductible = $15,000 out of pocket
Many homeowners don't realize they have a percentage-based hurricane deductible until they file a claim. Check your declarations page right now—look for "Hurricane Deductible" or "Wind/Hail Deductible."
When Does the Hurricane Deductible Apply?
Your hurricane deductible typically applies when:
- The National Weather Service issues a hurricane watch or warning for your area
- Damage occurs within a specific timeframe (usually 12-72 hours) after the watch/warning
If wind damage occurs outside the hurricane watch/warning period, your standard deductible applies instead.
Can You Lower Your Hurricane Deductible?
Yes, but it costs more. You can often reduce your hurricane deductible from 5% to 2% or even a flat $2,500 by paying a higher premium. If you can't afford a $15,000 deductible, ask your agent about lowering it.
Flood Insurance: Not Optional for Mobile/Baldwin County
If you live in Mobile or Baldwin County, flood insurance is essential—not optional. Here's why:
- Storm surge risk: Mobile Bay and the Gulf of Mexico can push 6-12 feet of water inland during major hurricanes
- Low elevation: Much of Mobile and Baldwin County is at or near sea level, making flooding likely during heavy rain
- Historical flooding: Hurricane Sally (2020), Hurricane Ivan (2004), and Hurricane Katrina (2005) all caused catastrophic flooding in the area
How Much Does Flood Insurance Cost?
Flood insurance costs vary based on your flood zone and home's elevation:
- High-risk zones (Zone A/AE/VE): $1,500-4,000/year
- Moderate-risk zones (Zone X shaded): $600-1,200/year
- Low-risk zones (Zone X unshaded): $400-700/year
Important: NFIP policies normally have a 30-day waiting period, with specified exceptions; private policies have insurer-specific timing. Don't wait until a hurricane is approaching—buy flood insurance now, before hurricane season starts.
What to Do Before Hurricane Season
Don't wait until a hurricane is approaching to review your coverage. Here's what Mobile and Baldwin County homeowners should do now:
- Review your declarations page and confirm your dwelling coverage limit reflects current rebuilding costs (not your home's market value).
- Check your hurricane/wind deductible and make sure you can afford it. If not, ask about lowering it.
- Purchase flood insurance if you don't already have it. Confirm the waiting period and effective date; NFIP normally has a 30-day wait with specified exceptions.
- Add extended replacement cost coverage if you don't already have it. Construction costs have increased 35-40% since 2020.
- Upgrade to replacement cost coverage for personal property instead of actual cash value.
- Document your belongings with photos or video. Walk through every room and photograph valuables, furniture, and electronics. Store the photos in cloud storage.
- Create a home inventory listing major items, purchase dates, and estimated values. This makes filing a claim much faster.
- Review your auto insurance and make sure you have comprehensive coverage for vehicle damage from hurricanes.
What to Do When a Hurricane Approaches
When a hurricane watch or warning is issued for Mobile or Baldwin County:
- Secure your property. Board up windows, bring in outdoor furniture, trim trees, and clear gutters.
- Document your home's condition. Take photos and videos of your home, belongings, and property before the storm. This proves the damage was caused by the hurricane.
- Review your insurance policies. Know your coverage limits, deductibles, and claims process before the storm hits.
- Evacuate if ordered. Your life is more valuable than any property. Follow evacuation orders from local authorities.
- Keep receipts for evacuation expenses. While most policies don't cover pre-storm evacuation, keep receipts just in case.
What to Do After a Hurricane
If your Mobile or Baldwin County home is damaged by a hurricane:
- Ensure everyone is safe and wait for authorities to declare it safe to return.
- Document the damage with photos and videos before making any repairs.
- Prevent further damage. Cover broken windows and tarp damaged roofs. Save all receipts—your policy covers reasonable temporary repairs.
- Call your insurance agent immediately to file a claim. Don't wait days or weeks.
- File separate claims for wind damage (homeowners) and flood damage (flood insurance). They're handled by different insurers.
- Keep detailed records of all expenses, including hotel bills, meals, and temporary repairs.
- Be patient. After major hurricanes, adjusters are overwhelmed. It may take weeks to get an inspection scheduled.
The Bottom Line
If you live in Mobile or Baldwin County, hurricane season is a reality every summer and fall. Standard homeowners insurance covers wind damage but does NOT cover flood damage—and flood insurance is not optional in coastal Alabama.
The three most common mistakes we see:
- No flood insurance to cover storm surge and rising water
- High percentage-based hurricane deductibles that homeowners can't afford
- Inadequate dwelling coverage that doesn't reflect current rebuilding costs
Don't wait until a hurricane is approaching to review your coverage. Take 15 minutes this week to review your policy, check your deductibles, purchase flood insurance, and make sure you're protected before the next storm.
Need help reviewing your hurricane coverage? Call TCDS Insurance at (205) 847-5616. We'll check your wind deductible, flood insurance, and coverage limits to make sure you're protected before hurricane season.
Get Hurricane-Ready Before the Next Storm
We'll review your wind deductible, flood insurance, and coverage limits to make sure you're protected. Don't wait until a hurricane is approaching.
Related Articles
Frequently asked questions
Does homeowners insurance cover hurricane damage in Mobile Alabama?
Yes, standard homeowners insurance covers wind damage from hurricanes, including roof damage, exterior walls, windows, and interior damage from rain entering through wind-damaged openings. However, it does NOT cover flood damage from storm surge or rising water. You need separate flood insurance for that, which is essential for Mobile and Baldwin County residents.
What is a hurricane deductible and how much is it?
Hurricane deductibles in Mobile and Baldwin County are typically 2-5% of your dwelling coverage, not a flat dollar amount. On a $300,000 home, a 2% deductible means you pay $6,000 out of pocket, 3% = $9,000, and 5% = $15,000. The deductible applies when the National Weather Service issues a hurricane watch or warning for your area. Check your declarations page for your specific hurricane deductible.
Do I need flood insurance in Mobile and Baldwin County?
Yes, flood insurance is essential for Mobile and Baldwin County residents. Storm surge from Mobile Bay and the Gulf of Mexico can push 6-12 feet of water inland during major hurricanes. Much of the area is at or near sea level. Hurricane Sally (2020), Hurricane Ivan (2004), and Hurricane Katrina (2005) all caused catastrophic flooding. Homeowners insurance does NOT cover flood damage—you need a separate flood insurance policy.
How much does flood insurance cost in Mobile Alabama?
Flood insurance in Mobile and Baldwin County costs $1,500-4,000 per year for high-risk zones (Zone A/AE/VE), $600-1,200 for moderate-risk zones, and $400-700 for low-risk zones. NFIP flood insurance normally has a 30-day waiting period, with specified exceptions; so don't wait until a hurricane is approaching—buy it now before hurricane season starts.
When is hurricane season in Mobile Alabama?
Atlantic hurricane season runs from June 1 through November 30, with peak activity from August through October. Mobile and Baldwin County have been hit by multiple major hurricanes including Hurricane Sally (2020), Hurricane Zeta (2020), Hurricane Ivan (2004), and Hurricane Katrina (2005). Residents should review insurance coverage and prepare evacuation plans before June 1 each year.