Do I Need Flood Insurance in Birmingham? The Honest Answer
Birmingham isn't on the coast, but flash flooding from heavy rain causes millions in damage annually. Here's who actually needs flood insurance—and who's wasting money.
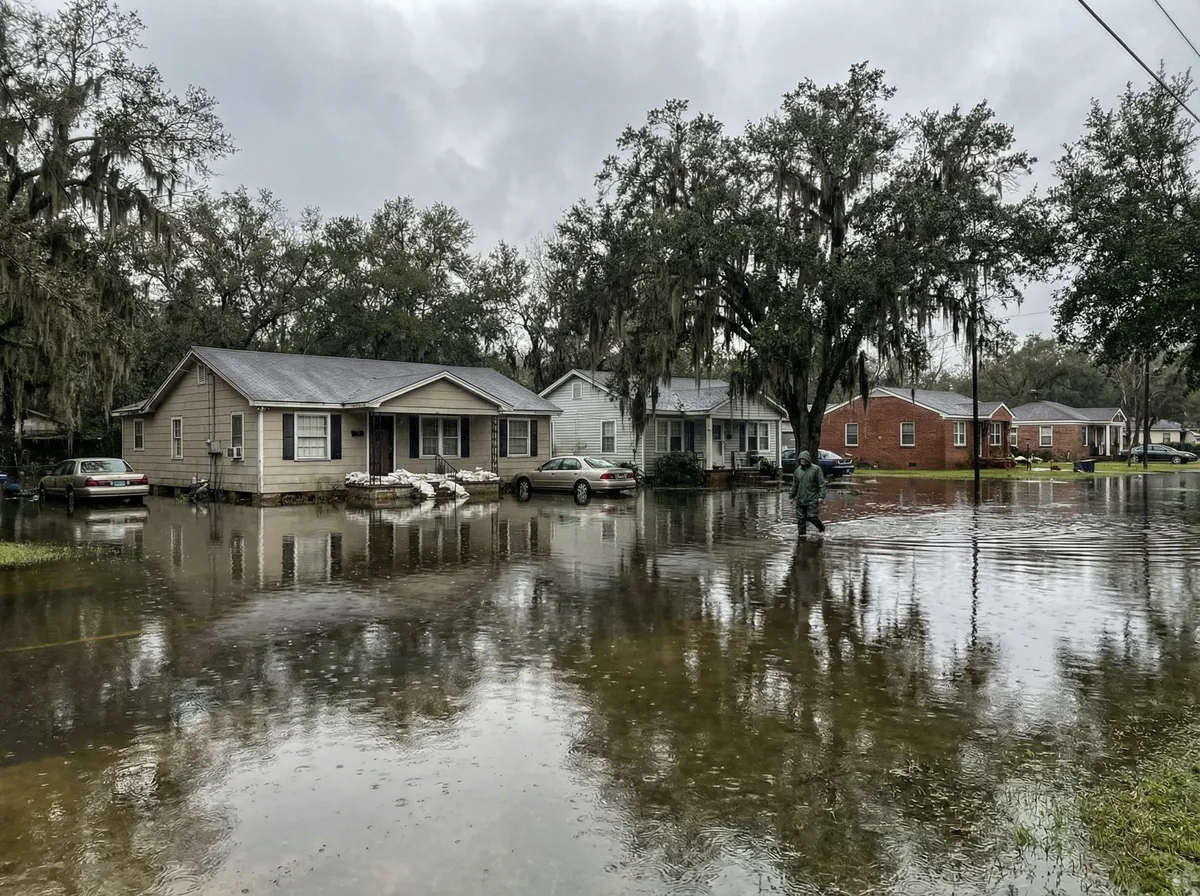
"Do I need flood insurance?" is one of the most common questions we get from Birmingham homeowners. The short answer: It depends on where you live and whether you have a mortgage. But the real answer is more nuanced—and your lender's requirement doesn't always match your actual flood risk.
This article explains who is required to buy flood insurance in Birmingham, who should buy it voluntarily, and who can safely skip it. We'll also cover what flood insurance actually costs and what it covers (and doesn't cover).
First: Homeowners Insurance Does NOT Cover Flood Damage
Before we discuss who needs flood insurance, let's clear up the biggest misconception:
Standard homeowners insurance does NOT cover flood damage. If water enters your home from the ground up—whether from heavy rain, overflowing creeks, or storm surge—your homeowners policy won't pay a dime.
Homeowners insurance covers water damage from:
- Burst pipes inside your home
- Roof leaks from storm damage
- Overflowing toilets or washing machines
But if rainwater floods your basement, or a nearby creek overflows and water enters your home, that's flood damage—and you need a separate flood insurance policy.
Who Is Required to Buy Flood Insurance?
If you have a mortgage from a federally backed lender (which is most mortgages), you're required by law to buy flood insurance if your home is in a Special Flood Hazard Area (SFHA)—also called a "high-risk flood zone."
What Are Flood Zones?
FEMA divides the country into flood zones based on historical flood data and topography:
- Zone A, AE, AH, AO: High-risk flood zones with a 1% annual chance of flooding (called the "100-year floodplain"). Flood insurance is required if you have a mortgage.
- Zone X (shaded): Moderate-risk zones with a 0.2% annual chance of flooding (called the "500-year floodplain"). Flood insurance is not required, but recommended.
- Zone X (unshaded) or Zone C: Low-risk zones with minimal flood risk. Flood insurance is not required, but still available.
How to check your flood zone: Go to FEMA's Flood Map Service Center (msc.fema.gov) and enter your Birmingham address. Your flood zone will be displayed on the map.
Birmingham's Flood Risk
Birmingham isn't coastal, but it still has flood risk from:
- Flash flooding from heavy rainfall (Birmingham averages 54 inches of rain per year)
- Creek and stream overflow (Village Creek, Valley Creek, Five Mile Creek, Shades Creek)
- Poor drainage in older neighborhoods with inadequate stormwater infrastructure
According to FEMA, approximately 8-12% of Birmingham homes are in high-risk flood zones (Zone A/AE). If you're in one of these zones and have a mortgage, you're required to buy flood insurance.
Who Should Buy Flood Insurance Voluntarily?
Even if you're not required to buy flood insurance, you might want to consider it if:
1. You're in a Moderate-Risk Zone (Zone X Shaded)
Moderate-risk zones have a 0.2% annual chance of flooding—which sounds low, but over a 30-year mortgage, that's a 6% chance of flooding. And here's the kicker: 25% of flood claims come from moderate- and low-risk zones, according to FEMA.
Flood insurance is cheaper in moderate-risk zones ($400-600/year for $250,000 in coverage), and it can save you tens of thousands if your home floods.
2. You Live Near a Creek or Low-Lying Area
If your Birmingham home is near Village Creek, Valley Creek, Five Mile Creek, Shades Creek, or any drainage area, you're at higher risk for flash flooding—even if you're not in an official flood zone.
FEMA flood maps are based on historical data and don't always account for recent development, increased impervious surfaces (pavement), or climate change. If your neighborhood has flooded in the past 10-20 years, consider buying flood insurance.
3. You Have a Finished Basement
Basements are especially vulnerable to flooding in Birmingham. Even homes outside flood zones can experience basement flooding from heavy rain overwhelming drainage systems.
If you have a finished basement with expensive furniture, electronics, or living space, flood insurance can cover the cost to replace damaged belongings and repair water damage.
4. You're Buying a Home and Want Protection During Closing
NFIP policies normally have a 30-day waiting period, but qualifying mortgage transactions can avoid that wait. Certain renewal increases, map changes, and post-wildfire flooding also have exceptions. For a Birmingham purchase, confirm the application, payment, and effective-date requirements before closing. Private flood policies have insurer-specific timing.
Who Can Skip Flood Insurance?
You can probably skip flood insurance if:
- You're in a low-risk zone (Zone X unshaded) with no history of flooding in your neighborhood
- You own your home outright (no mortgage) and don't live near water
- Your home is on a hill or elevated area with good drainage
- You have significant savings to cover potential flood damage out of pocket
That said, flood insurance is relatively affordable in low-risk zones ($400-700/year), and it can save you $50,000+ if your home floods. It's worth considering even if you're not required to buy it.
What Does Flood Insurance Cover?
Flood insurance through the National Flood Insurance Program (NFIP) covers:
Building Coverage (Up to $250,000)
- Foundation and structure
- Electrical and plumbing systems
- HVAC equipment, water heater, furnace
- Built-in appliances (dishwasher, range)
- Permanently installed carpeting and drywall
Contents Coverage (Up to $100,000)
- Furniture, clothing, and electronics
- Portable appliances (washer, dryer, portable AC)
- Curtains, area rugs, and artwork
What Flood Insurance Does NOT Cover
- Temporary living expenses (hotel, meals) while your home is being repaired
- Finished basements (limited coverage—drywall, flooring, and contents are covered, but not finished living space)
- Swimming pools, hot tubs, and landscaping
- Detached structures (garages, sheds) unless separately insured
- Currency, precious metals, and valuable papers
How Much Does Flood Insurance Cost in Birmingham?
Flood insurance costs vary based on your flood zone, home's elevation, and coverage limits:
- High-risk zones (Zone A/AE): $1,200-2,500/year for $250,000 building coverage + $100,000 contents
- Moderate-risk zones (Zone X shaded): $500-800/year
- Low-risk zones (Zone X unshaded): $400-600/year
Pro tip: Flood insurance premiums are the same whether you buy through FEMA's National Flood Insurance Program (NFIP) or a private carrier. Shop both options to compare coverage and pricing.
NFIP vs. Private Flood Insurance
You have two options for flood insurance:
National Flood Insurance Program (NFIP)
- Government-backed program administered by FEMA
- Maximum coverage: $250,000 building + $100,000 contents
- Normally a 30-day waiting period, with specified NFIP exceptions
- Standard pricing based on flood zone and elevation
Private Flood Insurance
- Offered by private insurance companies (not government-backed)
- Higher coverage limits available (up to $1 million+)
- Waiting periods vary by private insurer and policy
- Additional coverage options (temporary living expenses, replacement cost for contents)
Which should you choose? If your home is worth more than $250,000 or you want additional coverage options, private flood insurance might be better. Otherwise, NFIP is a solid, affordable option.
The Bottom Line
Here's the honest answer to "Do I need flood insurance in Birmingham?":
- You're required to buy it if you have a mortgage and live in a high-risk flood zone (Zone A/AE)
- You should strongly consider it if you're in a moderate-risk zone, live near a creek, or have a finished basement
- You can probably skip it if you're in a low-risk zone with no flooding history and own your home outright
Flood insurance is one of those coverages that seems unnecessary—until you need it. And when you need it, you really need it. A single flood can cause $50,000-100,000+ in damage, and without flood insurance, you'll pay every penny out of pocket.
Don't assume your homeowners insurance covers flooding. It doesn't. And don't assume you're safe just because you're not on the coast. Birmingham's flash flooding and creek overflow cause millions in damage every year.
Want to check your flood risk and get a quote? Call TCDS Insurance at (205) 847-5616. We'll look up your flood zone, explain your options, and get you quotes from both NFIP and private carriers.
Check Your Flood Risk Today
We'll look up your Birmingham address, check your flood zone, and explain whether you need flood insurance.
Related Articles
Coverage & Local Resources
Frequently asked questions
Does homeowners insurance cover flood damage in Birmingham?
No, standard homeowners insurance does NOT cover flood damage. If water enters your home from the ground up—whether from heavy rain, overflowing creeks, or storm surge—your homeowners policy won't pay. You need a separate flood insurance policy through the National Flood Insurance Program (NFIP) or a private carrier.
Do I need flood insurance in Birmingham Alabama?
It depends on your flood zone and mortgage status. You're required to buy flood insurance if you have a mortgage and live in a high-risk flood zone (Zone A/AE). You should strongly consider it if you're in a moderate-risk zone, live near Village Creek, Valley Creek, Five Mile Creek, or Shades Creek, or have a finished basement. Approximately 8-12% of Birmingham homes are in high-risk flood zones.
How much does flood insurance cost in Birmingham?
Flood insurance costs vary by flood zone: High-risk zones (Zone A/AE) cost $1,200-2,500 per year for $250,000 building coverage plus $100,000 contents. Moderate-risk zones cost $500-800 per year. Low-risk zones cost $400-600 per year. Prices are the same whether you buy through NFIP or a private carrier.
How long does it take for flood insurance to take effect?
NFIP policies normally have a 30-day waiting period. Exceptions can apply to qualifying mortgage transactions, certain renewal coverage increases, qualifying flood-map changes, and qualifying post-wildfire flooding. Private flood insurers set their own waiting periods and binding rules. Confirm the effective date before relying on coverage; buying a policy does not insure an existing loss.
What does flood insurance cover?
NFIP flood insurance covers up to $250,000 for building coverage (foundation, structure, electrical, plumbing, HVAC, built-in appliances) and up to $100,000 for contents coverage (furniture, clothing, electronics, portable appliances). It does NOT cover temporary living expenses, finished basements, swimming pools, landscaping, or detached structures unless separately insured.