
Tennessee Flood Risk Beyond Nashville: What Every Homeowner Needs to Know
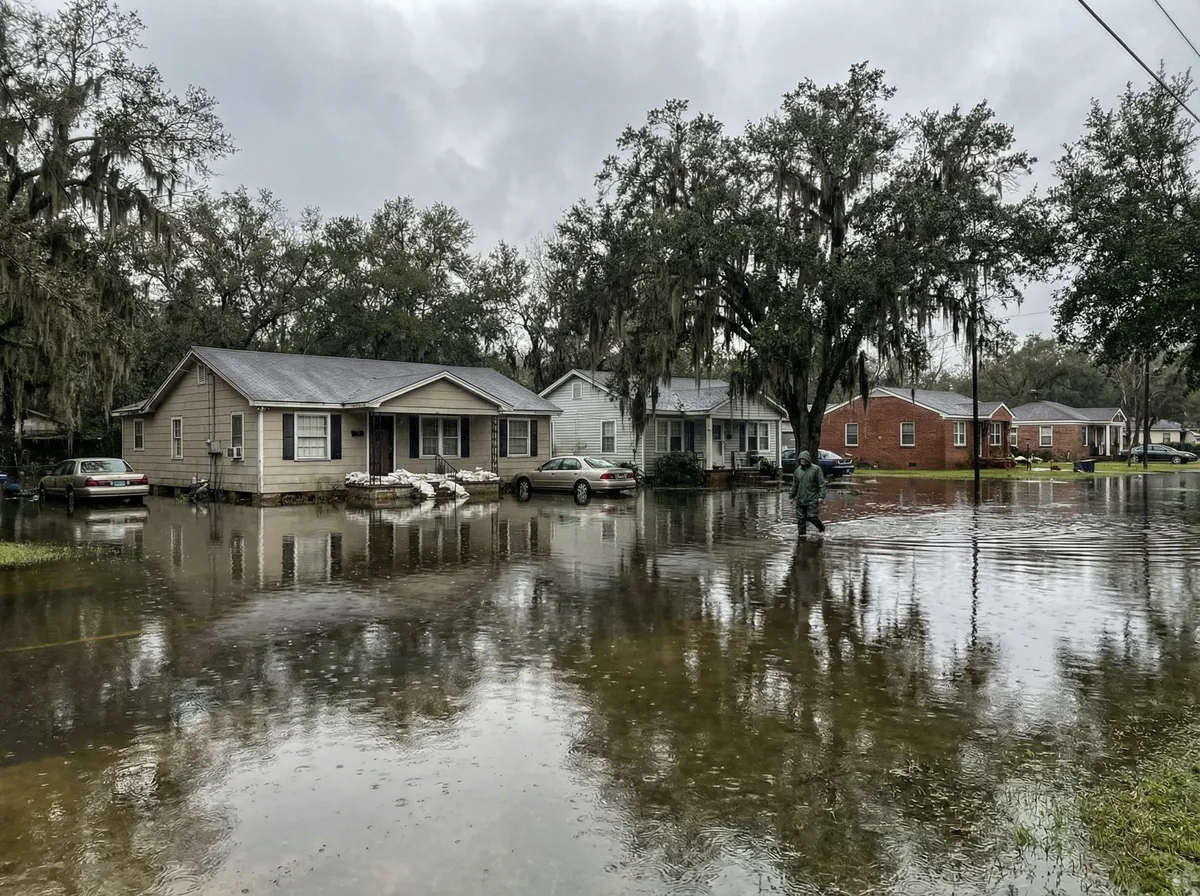
The May 2010 Nashville flood was a 1,000-year rainfall event that killed 26 people and caused $2 billion in damage. Over 13 inches of rain fell in two days, the Cumberland River crested nearly 12 feet above flood stage, and more than 11,000 properties were damaged. Most of those homeowners had no flood insurance. But Nashville is not the only flood risk in Tennessee—the state's rivers, mountain streams, and rapidly developing urban areas create flood risk from Memphis to Knoxville.
This guide explains Tennessee's flood risk beyond the headlines, why standard homeowners insurance leaves you completely exposed, and how to choose between NFIP and private flood insurance for your specific situation.
Tennessee's Flood Risk: A Statewide Problem
Tennessee's flood risk is not limited to Nashville. The state has three distinct geographic regions, each with its own flood characteristics:
West Tennessee (Memphis Area)
The Mississippi River floodplain dominates West Tennessee. Memphis sits on the bluffs above the river, but surrounding areas—including Shelby County suburbs and the Hatchie River corridor—are highly flood-prone. The Wolf River and Nonconnah Creek systems create additional flash flood risk within the metro area. The 2011 Mississippi River flood reached its highest level in Memphis since 1937.
Middle Tennessee (Nashville Area)
The Cumberland River basin is the epicenter of Tennessee's flood risk. Nashville's rapid growth has dramatically increased impervious surfaces, channeling more water into creeks and the Cumberland River during heavy rain events. The 2010 flood proved that even areas well outside FEMA flood zones can experience catastrophic flooding. Mill Creek, Harpeth River, and Stones River are all significant flood sources.
East Tennessee (Knoxville/Chattanooga Area)
The Tennessee River corridor through Chattanooga and Knoxville creates riverine flood risk, while the Great Smoky Mountains and Cumberland Plateau generate dangerous flash floods in narrow valleys. Mountain streams can rise 10-15 feet in hours during heavy rainfall. The August 2012 Chattanooga floods and repeated flash flooding in Gatlinburg demonstrate the risk.
Tennessee Flood Facts
- $2 billion in damage from the 2010 Nashville flood alone
- 11,000+ properties damaged in the 2010 Nashville flood
- 26 deaths across Tennessee from the May 2010 floods
- $1.1 billion in estimated annual flood losses statewide
- 40% of NFIP claims nationally come from outside high-risk flood zones
Lessons from the 2010 Nashville Flood
The 2010 Nashville flood taught Tennessee homeowners several painful lessons that remain relevant today:
- Flood zones are not flood-proof zones. Many of the hardest-hit areas in 2010 were outside FEMA-designated flood zones. Flood maps are based on historical data and do not account for new development, changing drainage patterns, or extreme rainfall events.
- Homeowners insurance does not cover floods. Thousands of Nashville homeowners discovered this after the 2010 flood. No matter how comprehensive your homeowners policy is, flood damage from rising water is excluded. Period.
- FEMA assistance is not insurance. After the 2010 flood, FEMA provided an average of $5,000-$8,000 per household in assistance—mostly as loans that had to be repaid. Compare that to the average flood damage of $50,000-$100,000+ per home.
- Check the effective date. NFIP policies normally have a 30-day waiting period, with specified exceptions. A warning does not itself prohibit an NFIP purchase, but a newly purchased policy does not cover an existing loss. Private insurers may restrict binding when a storm threatens.
NFIP vs. Private Flood Insurance in Tennessee
NFIP Coverage
- Dwelling coverage: Up to $250,000
- Contents coverage: Up to $100,000
- Waiting period: Normally 30 days; specified NFIP exceptions apply
- Basement: Limited to essential systems only
- Additional living expenses: Not included
- Payout basis: Actual cash value (depreciated)
Private Flood Insurance Advantages
- Higher limits: $500,000 to $5,000,000+ for dwelling
- Replacement cost: Full replacement instead of depreciated value
- Additional living expenses: Covered by most private policies
- Basement coverage: Full contents coverage available
- Waiting periods: Confirm the private insurer’s effective date and binding rules
- Potentially lower premiums: Especially for moderate-risk properties
Risk Rating 2.0 Impact on Tennessee
FEMA's Risk Rating 2.0 changed how NFIP premiums are calculated, moving from zone-based pricing to property-specific risk assessment. For many Tennessee homeowners—particularly those near the Cumberland River, Tennessee River, or in Nashville's urban core—this resulted in premium increases. If your NFIP premium increased significantly, a private flood policy may now be more affordable.
Do You Need Flood Insurance?
Even if not required by your mortgage, consider flood insurance if:
- You live within a mile of any river, creek, or stream
- Your neighborhood flooded in 2010, 2020, or any previous event
- You live in a low-lying area or at the bottom of a hill
- Significant new development has occurred upstream from your property
- You live in Nashville, Memphis, Chattanooga, or Knoxville metro areas
Protecting Your Tennessee Home
Your Tennessee Flood Insurance Checklist
- ☐ Check your FEMA flood zone at msc.fema.gov (but remember—floods happen outside zones)
- ☐ Get quotes from both NFIP and private flood carriers
- ☐ Compare coverage limits, deductibles, and payout basis (ACV vs. replacement cost)
- ☐ Ask about additional living expenses coverage (NFIP does not include it)
- ☐ Purchase flood insurance at least 30 days before you need it
- ☐ Document your belongings with photos and receipts (store in the cloud)
- ☐ Know your property's elevation relative to nearby waterways
- ☐ Consider a sump pump and backup power to reduce basement flood risk
The Bottom Line
Tennessee's flood risk extends far beyond Nashville and far beyond FEMA flood maps. The 2010 Nashville flood was a $2 billion reminder that flooding can devastate communities that never expected it. Standard homeowners insurance provides zero coverage for flood damage, and FEMA assistance after a flood averages less than $10,000—a fraction of what most homeowners need to recover.
Flood insurance through the NFIP or a private carrier is the only way to protect your home and belongings. With Risk Rating 2.0 changing pricing and private carriers offering competitive alternatives, now is the time to compare options and get covered—before the next flood, not after.
Need help finding the right flood insurance for your Tennessee home? Call TCDS Insurance at (615) 989-6444 or request a free quote below. We compare NFIP and private flood options to find the best coverage for your specific property.
Free Tennessee Flood Insurance Quote
We compare NFIP and private flood insurance options to find the best coverage at the best price for your Tennessee home. Most quotes are ready within 24 hours.
Related Articles
Frequently asked questions
Does homeowners insurance cover flood damage in Tennessee?
No. Standard homeowners insurance in Tennessee does not cover flood damage regardless of the cause—whether from river overflow, flash flooding, or tornado-related flooding. You need a separate flood insurance policy through the NFIP or a private carrier. This is true even if you live outside a FEMA-designated flood zone.
How much does flood insurance cost in Tennessee?
Under NFIP Risk Rating 2.0, flood insurance premiums in Tennessee range from $400 to $2,000+ per year depending on your property's specific flood risk, elevation, and distance from water sources. Properties in high-risk areas like the Nashville floodplain or along the Tennessee River pay significantly more. Private flood insurance may be cheaper for moderate-risk properties.
Is flood insurance required in Tennessee?
Flood insurance is required if you have a federally backed mortgage and your property is in a FEMA-designated Special Flood Hazard Area. However, the May 2010 Nashville floods proved that devastating flooding can occur far outside designated flood zones. About 40% of NFIP claims nationally come from outside high-risk zones.
What areas of Tennessee are most at risk for flooding?
Nashville and the Cumberland River basin are the highest-risk areas, as demonstrated by the catastrophic May 2010 floods. The Tennessee River corridor through Chattanooga and Knoxville, the Mississippi River floodplain in West Tennessee (Memphis area), and mountain streams in East Tennessee are also high-risk. Urban flash flooding is increasing in all major Tennessee cities.
What happened during the 2010 Nashville flood?
In May 2010, Nashville received over 13 inches of rain in two days—a 1,000-year rainfall event. The Cumberland River crested at 51.86 feet, nearly 12 feet above flood stage. The floods killed 26 people across Tennessee, caused $2 billion in damage in Nashville alone, and damaged over 11,000 properties. Many affected homeowners had no flood insurance.
Does Tennessee have a waiting period for flood insurance?
NFIP policies normally have a 30-day waiting period. Exceptions can apply to qualifying mortgage transactions, certain renewal coverage increases, qualifying flood-map changes, and qualifying post-wildfire flooding. Private flood insurers set their own waiting periods and binding rules. Confirm the effective date before relying on coverage; buying a policy does not insure an existing loss.









































